AWL review: leads, pricing and terms
AWL, short for All Web Leads, runs the InsuranceLeads.com, InsuranceQuotes and NetQuote brands and sells the shoppers who request quotes on its sites to agents as real-time web leads, live transfers and clicks. It covers personal lines, health, senior health, life, annuity, disability, long-term care and small business insurance.
Web leads are carrier-exclusive and go to two to four agents on average. An Austin contact center calls shoppers before live transfers and before Qualified Prospect leads, web leads it has called to confirm interest, and AWL also sells insurance to consumers through its own agency.
- Best for
- Agents who want shared web leads across many lines with no deposit and free geographic targeting
- Formats
- Real-time leads and live transfers
- Lines
- Life, health, senior health, Medicare, annuity, disability, long-term care, auto, home, renters, commercial and business benefits
- Shared or exclusive
- Web leads are carrier-exclusive and go to 2 to 4 agents on average. A live transfer reaches a single agent
- Price
- Base price per lead by line and package, with an optional Max Bid. Geographic filters are free, other filters cost extra
- To start
- No deposit or setup fee. Delivered leads are billed on the 1st and 16th, or sooner when a new agent reaches the $50 credit limit
- Contract
- No long-term contract
- Returns
- Up to 10 days, as account credit
- States
- Nationwide, by state, county, ZIP code and radius or area code
Our take
AWL fits agents who want a steady flow of shared web leads across many lines from one account, with no deposit and the option to add live transfers or clicks later. Geographic targeting is free, and you can cap volume by day, week, month or budget.
Most agents should start with one line and the package that matches the clients they write best, such as Preferred Plus auto, in a few ZIP codes or counties. Once cost per sale is clear, add filters or live transfers.
Ask your account manager which filters change the price for your line, and check your account on the 1st and 16th, when your card is billed for delivered leads.
Pros
- Web leads, live transfers and clicks from one account
- No deposit or setup fee
- Free geographic targeting by state, county, ZIP code, radius or area code
- Published sample leads for 10 lines
- Daily, weekly, monthly and budget caps
- Returns accepted within 10 days of delivery
Cons
- Web leads are shared, with two to four agents on average
- No published prices
- Filters beyond geography add to the price
- Returns come back as account credit only
Product details
| Product | Lines | Who gets it |
|---|---|---|
| Real-time web leads | Auto, home, health, life, final expense, renters, senior health, Medicare, annuity, disability, long-term care, commercial and business benefits | Carrier-exclusive, 2 to 4 agents on average |
| Live transfers (Qualified Concierge Calls) | All lines | One agent |
Live transfers
AWL's Qualified Concierge Calls start with a contact center rep who calls the shopper, confirms they want to talk to an agent now and transfers the call to you. You pay only for calls that connect, and you can set hourly and daily call limits.
Clicks
AWL also sells clicks through Qualified Insurance Traffic. Shoppers who have already filled out a quote form click through to your site, and you can have your own form pre-filled with their answers.
Getting started
- Create an account on InsuranceLeads.com or InsuranceQuotes. There's no deposit or setup fee.
- Choose your lines and packages, then target by state, county, ZIP code and radius or area code, and add any filters.
- Set daily, weekly or monthly volume, a budget limit or hourly and daily call limits.
- Leads arrive by email, text, your online account or your CRM or rater.
- Your card is charged on the 1st and 16th, or sooner if you reach your credit limit, for leads already delivered.
Pricing
AWL doesn't publish prices. Each line has a base price per lead, and auto leads come in four packages from Preferred Plus to Non-Standard.
Geographic targeting is free, and hundreds of optional filters add to the base price. You pay only for leads you receive.
Max Bid is an optional per-profile setting. Set the most you'd pay in total per lead or call.
If another agent goes for the same lead or call, AWL raises your price only as much as it takes to beat theirs, and never past your Max Bid. Turn it on where there's a lot of competition and you want more volume.
| Item | Cost |
|---|---|
| Setup fee and deposit | None |
| Starting credit limit | $50 for new agents |
| Billing | Card charged on the 1st and 16th, or when you reach your credit limit, for leads already delivered |
| Filters | Geographic filters are free. Other filters add to the lead price |
| Service Plan | Optional monthly fee, with pausing for up to 10 days at a time and weekend discounts |
Pricing is by quote
AWL doesn't publish a price we can put into a calculator, so your cost comes from AWL's quote.
What sets the price
- Quoted base prices with optional Max Bid
- You pay for leads, calls and clicks
- Premium prospects add 25% to the price
- Qualified prospects add 50% to the price
- Geographic filters are free. Other filters cost extra
To see what other vendors in the category charge, see the insurance lead companies cost guide.
Sample leads and filters
InsuranceLeads.com publishes a sample lead for life, health, senior health, annuity, disability, long-term care, auto, home, renters and commercial insurance. Every lead includes the shopper's name, email, daytime and evening phone and address.
Life leads
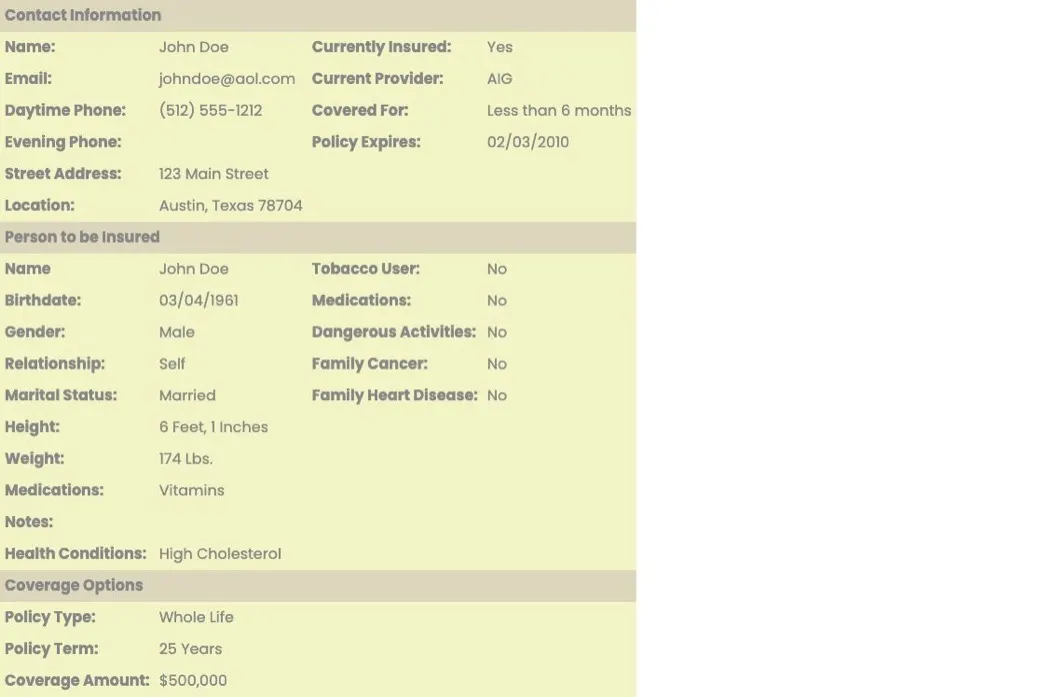
The life lead has current insurance, tobacco use, birthdate, gender, height, weight, medications and health conditions. It also asks about dangerous activities and whether cancer or heart disease runs in the family. At the bottom you see the policy type, term and coverage amount the shopper picked.
Health leads
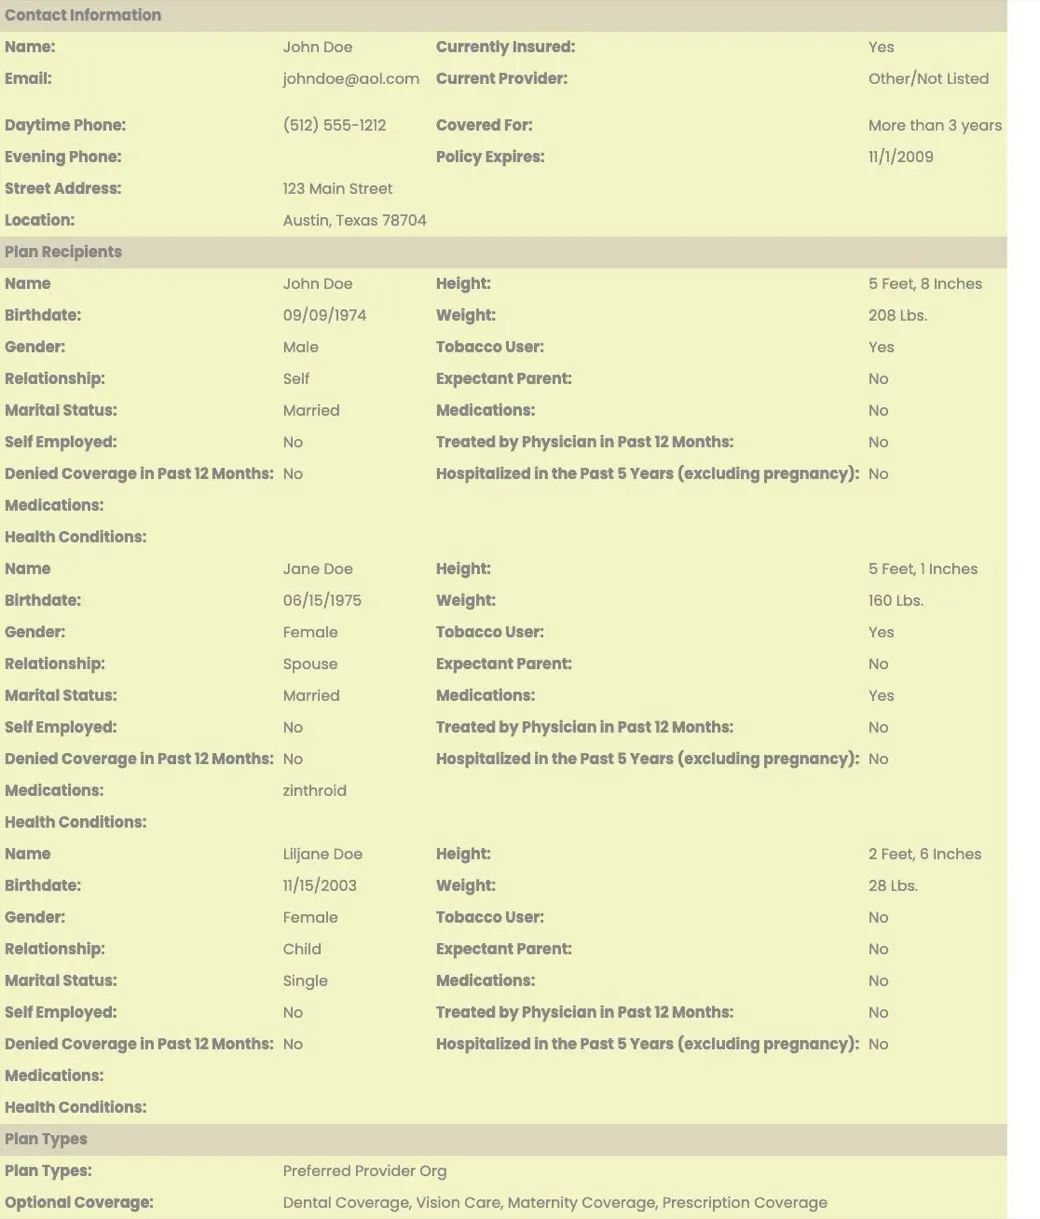
Health leads start with current insurance. Then each applicant gets listed with height, weight, birthdate, gender, tobacco use, pregnancy, marital status, medications, self-employment and health conditions. The plan types and optional coverage they want come at the end.
Senior health leads
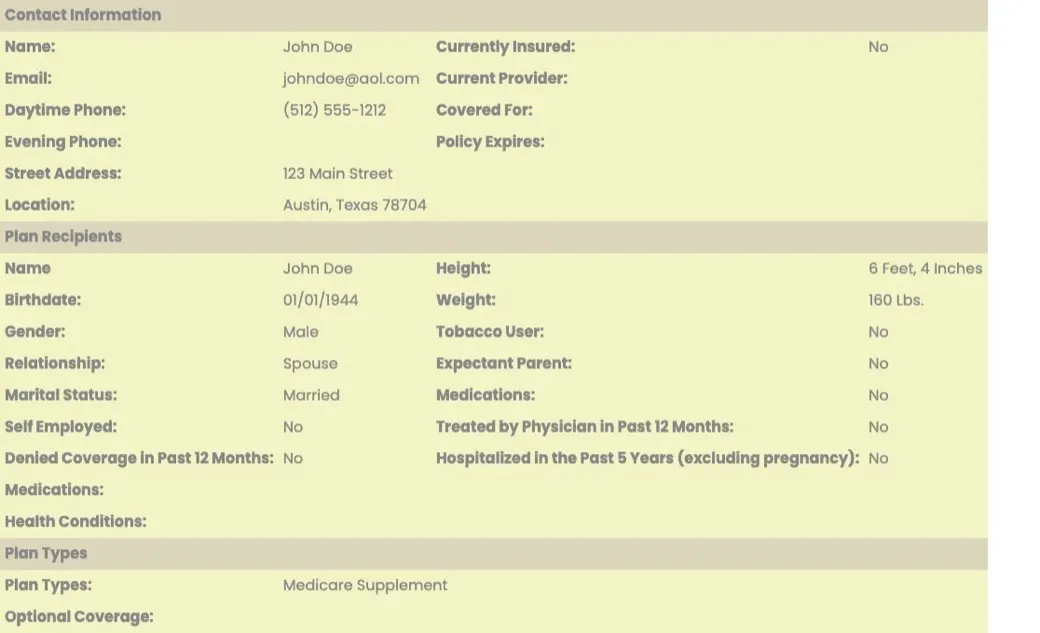
Senior health uses the same layout as health. Expect current insurance, height, weight, birthdate, gender, tobacco use, marital status, medications and health conditions, along with the plan types wanted.
Annuity leads
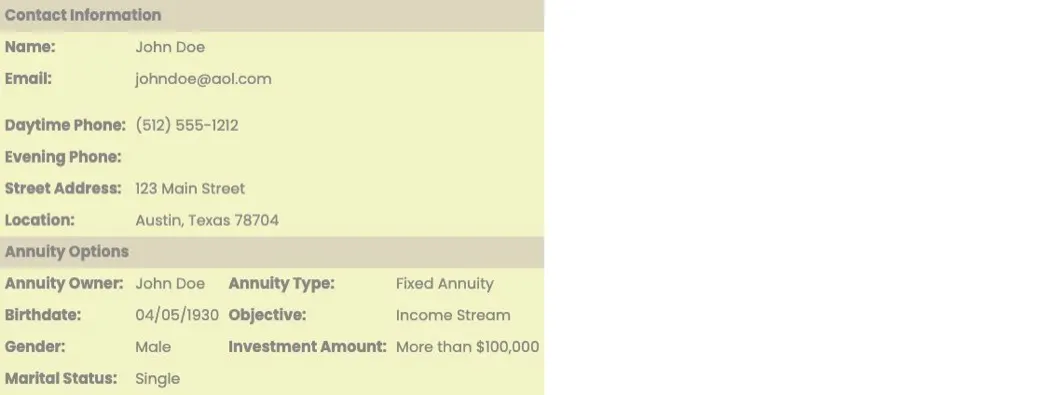
The annuity lead shows if the shopper already owns an annuity, then the annuity type and objective. Birthdate, gender, marital status and the amount to invest round it out.
Disability leads
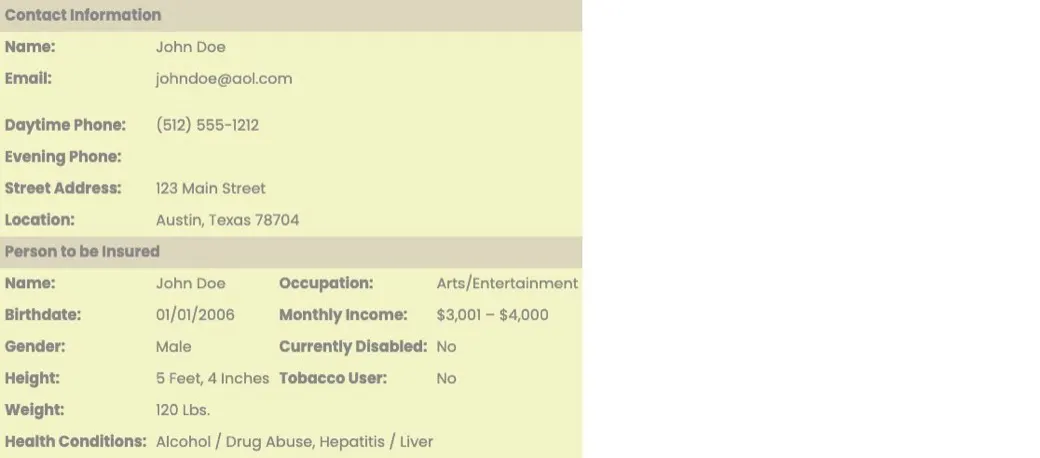
Disability leads list occupation and monthly income. They also say whether the shopper is currently disabled and carry birthdate, gender, height, weight, tobacco use and health conditions.
Long-term care leads
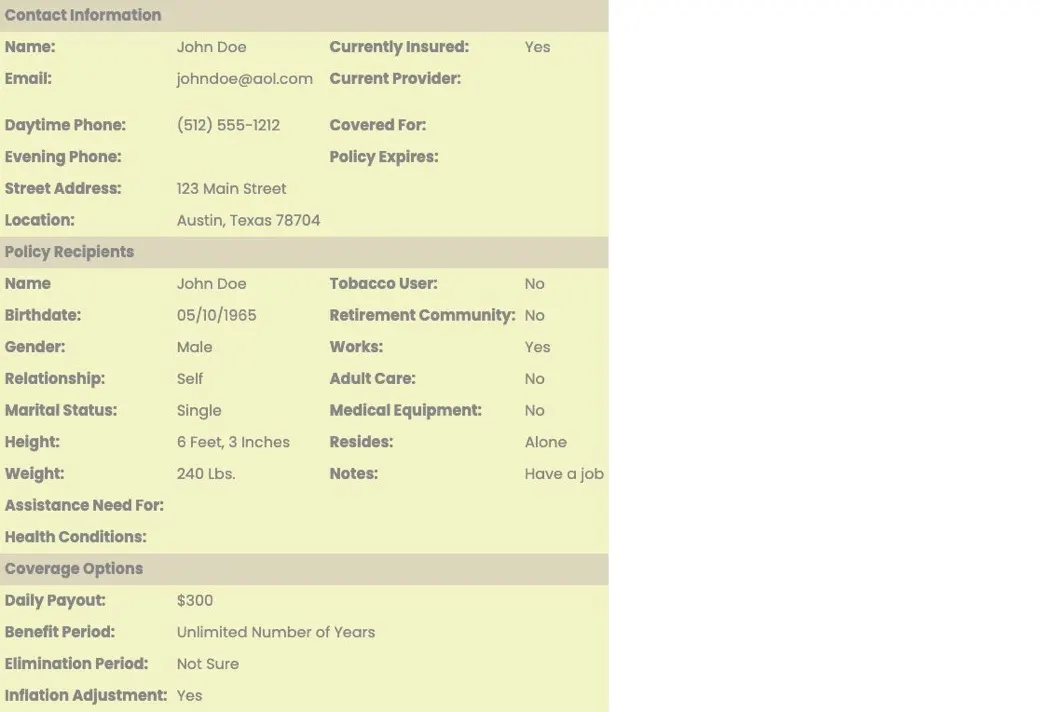
Long-term care leads cover current insurance, tobacco use, birthdate, living situation, work, adult care, medical equipment, assistance needs, height, weight and health conditions. The shopper also states the daily payout, benefit period, elimination period and inflation adjustment they want.
Auto leads
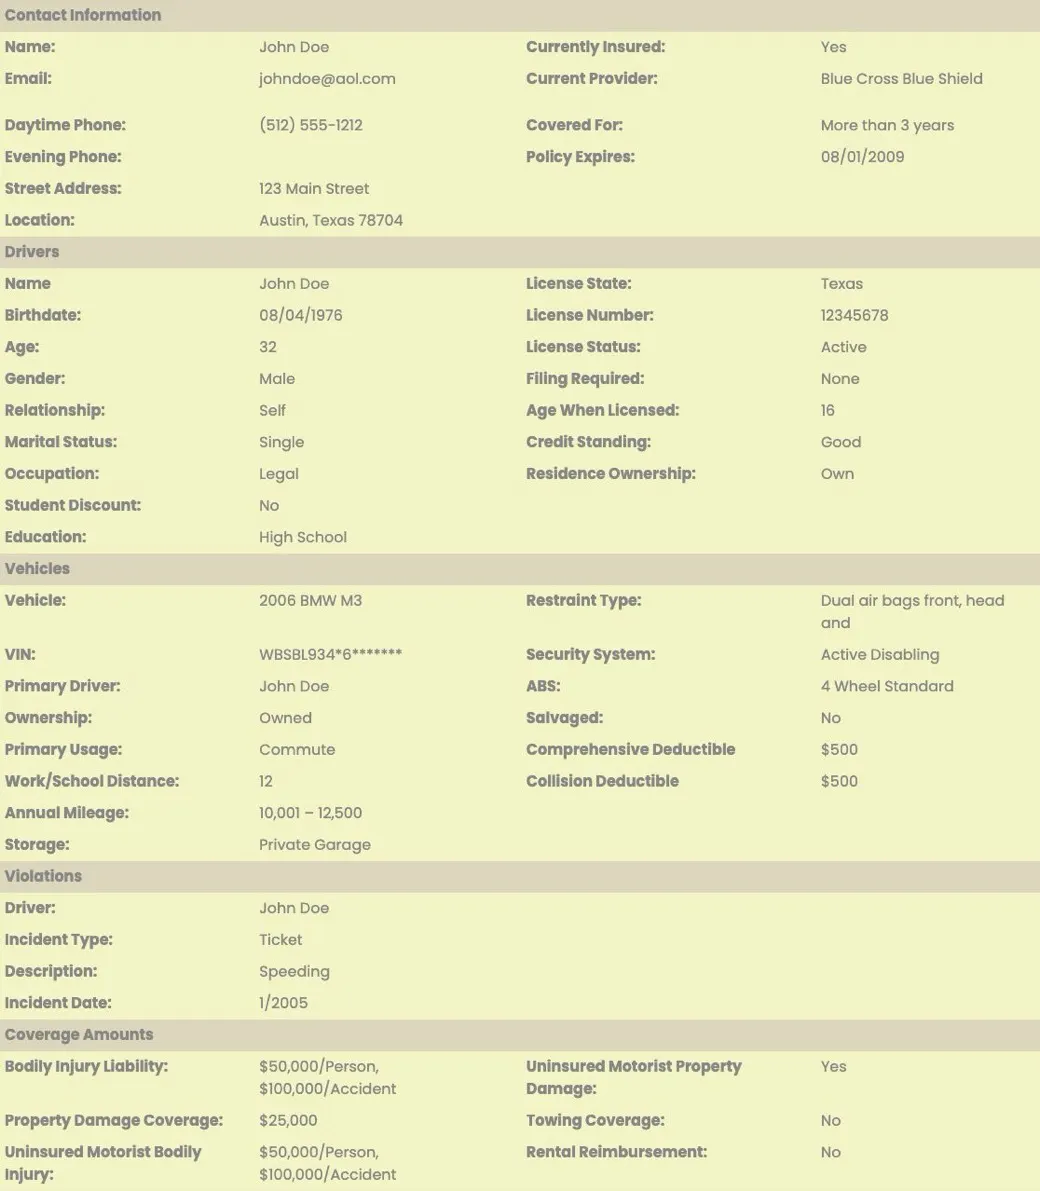
The auto lead shows current insurance and how long the shopper has had it, then each driver's license details, credit standing and homeownership, each vehicle with VIN, use, mileage and deductibles, any violations and the liability limits wanted. Auto leads come in four packages, Preferred Plus, Preferred, Standard Plus and Non-Standard, set by driver age, insurance history and driving record.
Home leads
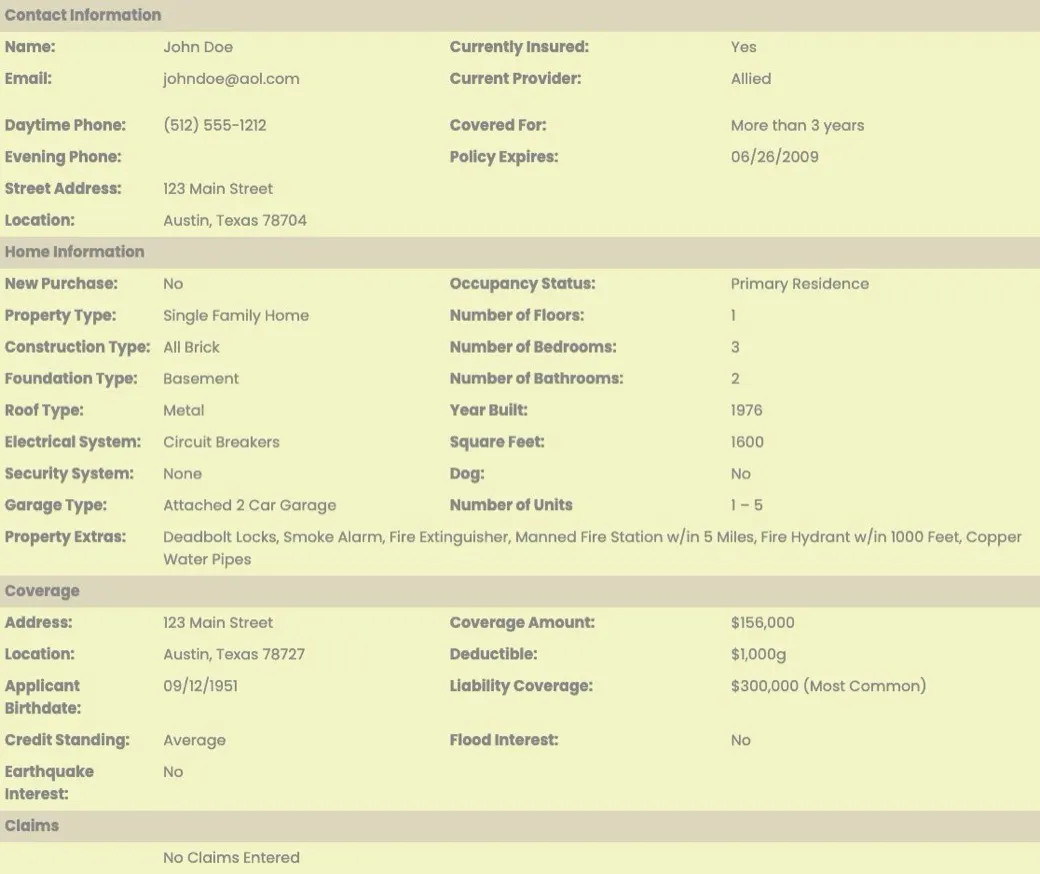
The home lead adds whether it's a new purchase, occupancy, property type, floors, construction, bedrooms and bathrooms, foundation, roof, year built, electrical system, square footage, security system, dog and garage, plus the coverage amount, deductible and liability wanted, credit standing and interest in flood or earthquake coverage.
Renters leads
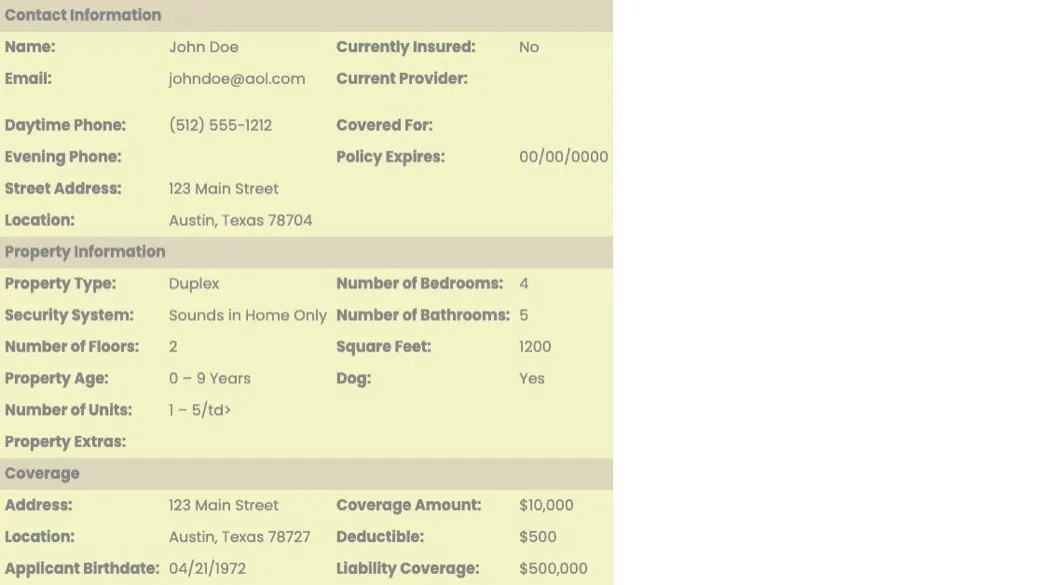
A renters lead is about the place itself, meaning property type, bedrooms and bathrooms, floors, square footage, property age and number of units. It also notes whether there is a security system or a dog, and the coverage amount, deductible and liability wanted.
Business property and casualty leads
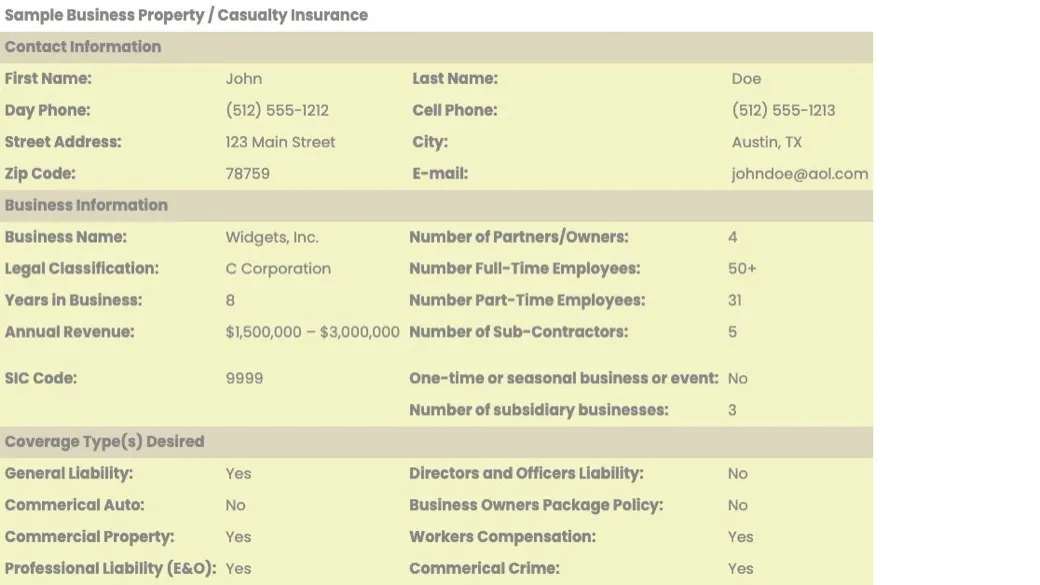
A business lead names the company and gives its legal classification, owners or partners, full-time and part-time staff, years in business, annual revenue, subcontractors, SIC code, seasonal work and subsidiaries. It closes with the coverage types the owner is after, such as general liability, commercial property, workers' comp and professional liability.
Filters
Geographic filters are free on every line. Other filters are priced per line: auto offers multi-line, premium quality only and high risk only.
Home filters include insurance status, age of home, flood or earthquake interest, new purchases, mobile or manufactured homes, claims, credit and property type. Health, senior health, disability and long-term care filters cover age, BMI, tobacco use and major health conditions, and business leads filter by company size and coverage type.
Lead quality checks
Most shoppers come from AWL's own sites through search engines such as Google and Bing, with screened partners sending the rest. AWL checks for bogus names, phones and emails, matches ZIP codes against the address, the phone prefix and the IP address, and pings phone numbers during the day. Its contact center calls shoppers before live transfers and Qualified Prospect leads to confirm they asked for a quote and want to talk now.
Shoppers agree in AWL's terms to be contacted by phone, text and email, including automated calls and texts, even if their number appears on the Do Not Call list.
Delivery and integrations
Leads arrive by email, text and your online account, or post into your CRM, rater or quoting engine, seven days a week. Live transfers ring through to your phone.
Lead returns
You can return a lead within 10 days of delivery, and approved returns come back as full-price account credit toward future leads. Accepted reasons include disconnected, fax or wrong numbers, an AWL duplicate from the past 30 days, another agent testing, a student project, obviously fake contact details, a language barrier, a shopper who didn't request a quote and a shopper already insured by your primary carrier.
For live transfers, you can submit a call for review if the caller disconnected, failed a screening question, wasn't answered, came in while your account was paused or was a home call that turned out to be renters.
Contract and cancellation details
There's no long-term contract. To stop, tell InsuranceLeads.com to close your account, and pause lead flow first so nothing new arrives while it closes. The optional Service Plan adds pausing for up to 10 days at a time and weekend discounts for a monthly fee.
AWL alternatives
These lead companies sell similar lines and lead types.
Often compared with
See every option in insurance lead companies.
Frequently asked questions
How much do InsuranceLeads.com leads cost?
AWL doesn't publish prices. Each line has a base price per lead, geographic filters are free and other filters add to the price.
You can also turn on the optional Max Bid for a profile, which raises your price only as far as needed to beat a competing agent, up to the limit you set. There's no deposit or setup fee.
Are InsuranceLeads.com leads exclusive?
Web leads are carrier-exclusive, so they go to only one agent per carrier, and two to four agents on average. A live transfer reaches a single agent.
Can I return bad InsuranceLeads.com leads?
Yes, within 10 days of delivery, for reasons such as wrong or disconnected numbers, duplicates, fake contact details or a shopper who didn't request a quote. Approved returns come back as account credit.
Does AWL require a contract?
No. There's no long-term contract, and you can end the account by letting InsuranceLeads.com know.
How we researched this review. We based this review on the terms and product pages published by AWL, reviewed in October 2026, together with our team's experience working with insurance agents and agency owners since 2008, including agents who have bought leads from AWL and many other providers.
Corrections
Vendors change their pricing all the time and they don't email us when they do. So if you see a price on here that's gone up, a plan AWL quit selling or a contract term that reads different now, let us know and send the link to the page where AWL has it. Somebody here pulls up that page and checks it before we change anything on ours.