NAPA E&O review for insurance agents: E&O cost, coverage and policy terms
E&O insurance pays to defend you, and pays the client, when a client says a mistake in your insurance work cost them money. NAPA, the National Association of Professional Agents, sells it to members on policies from CNA companies.
It fits life, health and Medicare agents first, with separate programs for solo P&C agents, small agencies and IMOs. The main programs publish their premiums online, with NAPA dues included.
- Best for
- Life, health and Medicare agents who need a certificate fast, plus solo P&C agents and small agencies
- Price
- From $355 a year for a newly licensed life and health agent, NAPA dues included
- Insurer
- CNA companies, placed through Gallagher Affinity
- Lines covered
- Life, health, Medicare, annuities, securities and P&C
- Policy form
- Claims-made and reported, so the claim must be made and reported while you are insured
- Admitted
- Yes on the direct programs, so a state guaranty fund backs claims if the insurer fails
- Newly licensed
- Lower rates in your first two years with under $100,000 in commissions
Our take
NAPA fits a life, health or Medicare agent who needs E&O on file before a carrier or IMO finishes contracting. You see the price before you apply, pay online and download the certificate once you're approved.
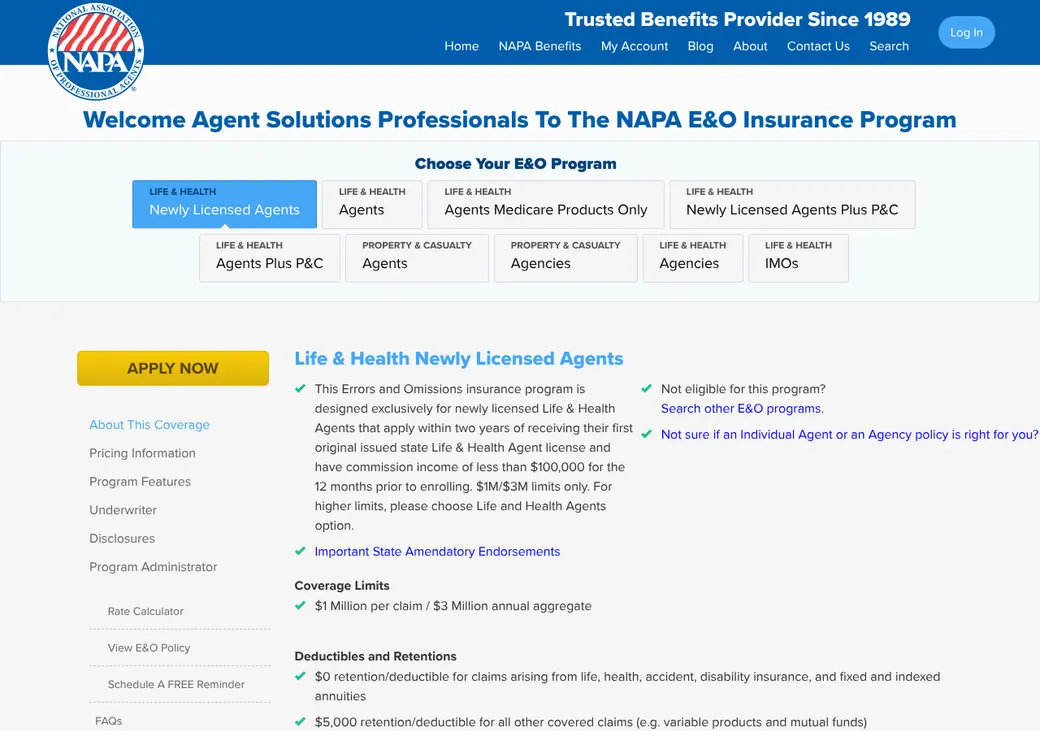
Most life and health agents buy Option A, which covers life, health and Medicare sales with no deductible. For $1 million per claim and $3 million a year, it costs $441 a year, or $355 in your first two years (October 2026 prices). Option B adds annuities and Option C adds variable products.
The limit to know is $1 million per claim with $3 million a year in total. Defense costs come out of that limit, so a long lawsuit leaves less for a settlement.
Pros
- Premiums for every main program are published before you apply
- Lower rates for newly licensed life and health agents
- $0 deductible on life, health and fixed annuity claims
- A free three-year tail after three years enrolled on life and health
- Certificate online as soon as you're approved
- Monthly payments by card or bank draft
Cons
- Defense costs reduce the limit on every program
- The insurer can settle a claim without your consent
- Published rates stop at $250,000 a year in commissions
- A P&C agent with other producers needs the agency program
- Admin fees and dues aren't refunded if you cancel
Who can buy
- Licenses
- The licenses each product you sell requires. Option C also needs your securities registrations
- Lines
- Pick the life and health option, P&C level or agency level that matches everything you sell
- Years licensed
- Newly licensed rates apply within two years of your first life and health license
- Agency size or revenue
- Published rates are for under $250,000 a year in commissions. Newly licensed rates need under $100,000 in the past 12 months
- Prior claims
- Life and health applicants can have no more than two claims in seven years. P&C applicants need a clean 10 years
- Membership required
- Yes. NAPA dues of $60 a year are part of each individual premium, not a separate bill
What it costs
| Program | Limit | Deductible | Paid in full | Monthly option |
|---|---|---|---|---|
| Option A, newly licensedLife, health and Medicare | $1M per claim, $3M a year | $0 | $355 | $126.25 down, then $26.25 a month |
| Option B, newly licensedAdds fixed and indexed annuities | $1M per claim, $3M a year | $0 | $434 | $132.87 down, then $32.83 a month |
| Option C, newly licensedAdds variable products and mutual funds | $1M per claim, $3M a year | $0, or $5,000 on securities | $602 | $146.87 down, then $46.83 a month |
| Option A, experiencedLife, health and MedicareWhere most life and health agents start | $1M per claim, $3M a year | $0 | $441 | $138 down, then $33 a month |
| Option B, experiencedAdds fixed and indexed annuities | $1M per claim, $3M a year | $0 | $524 | $144.92 down, then $39.92 a month |
| Option C, experiencedAdds variable products and mutual funds | $1M per claim, $3M a year | $0, or $5,000 on securities | $644 | $154.92 down, then $49.92 a month |
| Medicare onlyMedicare Advantage, Supplement and Part D | $1M per claim, $1M a year | $0 | $374 | $132.42 down, then $27.42 a month |
| Option A plus P&C, newly licensedLife and health with a small personal lines book | $1M per claim, $1M a year | $0, or $5,000 on P&C | $670 | $180 down, then $50 a month |
| Option B plus P&C, newly licensedAdds annuities | $1M per claim, $1M a year | $0, or $5,000 on indexed annuities and P&C | $750 | $186.67 down, then $56.67 a month |
| Option C plus P&C, newly licensedAdds annuities and securities | $1M per claim, $1M a year | $0, or $5,000 on indexed annuities, securities and P&C | $905 | $199.62 down, then $69.58 a month |
| Option A plus P&C, experiencedLife and health with a small personal lines book | $1M per claim, $1M a year | $0, or $5,000 on P&C | $765 | $192.50 down, then $57.50 a month |
| Option B plus P&C, experiencedAdds annuities | $1M per claim, $1M a year | $0, or $5,000 on indexed annuities and P&C | $845 | $199.17 down, then $64.17 a month |
| Option C plus P&C, experiencedAdds annuities and securities | $1M per claim, $1M a year | $0, or $5,000 on indexed annuities, securities and P&C | $970 | $209.62 down, then $74.58 a month |
| P&C agent, Level 1Admitted personal lines | $1M per claim, $1M a year | $5,000 | $680 | $199.17 down, then $49.17 a month |
| P&C agent, Level 2Adds admitted commercial lines | $1M per claim, $1M a year | $5,000 personal, $10,000 commercial | $830 | $211.67 down, then $61.67 a month |
| P&C agent, Level 3Adds specialty and surplus lines placements | $1M per claim, $1M a year | $25,000 | $1,130 | $236.67 down, then $86.67 a month |
| P&C agency, Level 1Admitted personal lines | $1M per claim, $1M a year | $5,000 | $980 | $257.12 down, then $82.08 a month |
| P&C agency, Level 2Adds admitted commercial lines | $1M per claim, $1M a year | $5,000 personal, $10,000 commercial | $1,205 | $275.87 down, then $100.83 a month |
| P&C agency, Level 3Adds specialty and surplus lines placements | $1M per claim, $1M a year | $5,000 to $25,000 | $1,705 | $317.50 down, then $142.50 a month |
| Life and health agency, Level 1Life, health, annuities, securities and personal lines | $1M per claim, $1M a year | $0, or $5,000 on annuities, securities and P&C | $1,530 | $302.92 down, then $127.92 a month |
| Life and health agency, Level 2Adds admitted commercial lines | $1M per claim, $1M a year | $0 to $10,000 by line | $1,830 | $327.92 down, then $152.92 a month |
| Life and health agency, Level 3Adds specialty and surplus lines placements | $1M per claim, $1M a year | $0 to $25,000 by line | $2,330 | $369.62 down, then $194.58 a month |
| Life and health IMOCovers the IMO and its exclusive downline | $1M per claim, $1M a year | $0, or $5,000 on indexed annuities and securities | $1,180 | $273.75 down, then $98.75 a month |
Premiums as of October 2026 from NAPA's pricing pages. Each one includes the $60 dues and the admin fee. Your own premium depends on your application and underwriting, so treat these as published rates, not a quote.
| Cost | Amount | Notes |
|---|---|---|
| NAPA membership dues | $60 a year | Included in every premium shown |
| Administration fee | $40 to $115 | Included. It runs higher for P&C, agency and IMO programs and is never refunded |
| Processing fee | $5 a month | Monthly plans only, inside the monthly amount. Agencies and IMOs pay $15 |
| Down payment | First month plus fees | Charged when you apply. It covers the first month, dues, admin fee and processing fee |
Compare the programs
| Individual life and health | Individual P&C | Agency and IMO | Sponsored groups | |
|---|---|---|---|---|
| Lines | Life, health, Medicare, annuities, securities | Personal and commercial P&C, life and health add-on | P&C or life and health, by level | Set by the sponsor |
| Admitted | Yes | Levels 1 and 2 | Levels 1 and 2 | Varies |
| Policy form | Claims-made and reported | Claims-made and reported | Claims-made and reported | Set by the sponsor |
| Top limit | $2M per claim | $1M per claim, $2M a year | $1M per claim, $3M a year | Set by the sponsor |
| Defense outside limits | Varies | |||
| Newly licensed pricing | Varies | |||
| Covers employees | Support staff only | Support staff only | Varies |
Sponsored programs run through a carrier, IMO or association. The sponsor sets the insurer, price and coverage. Some ask for your carrier writing number to confirm you're appointed.
Insurer and admitted status
- Issuing insurer
- One or more CNA companies. Your certificate names the exact one
- Admitted
- Yes on the life and health program and P&C Levels 1 and 2. Level 3 business placed with surplus lines insurers must go through a separate surplus lines broker
- Administrator
- NAPA runs the program. Gallagher Affinity is its licensed broker and administrator
- States
- All 50 states and U.S. territories for life and health. P&C endorsements vary by state
Policy form, prior acts and tail
Claims-made means the policy that is in force when a client makes a claim is the one that pays it. The retroactive date sets how far back the mistake can be.
- Policy form
- Claims-made and reported
- Retroactive date
- The day your continuous E&O coverage began, shown on your certificate
- Prior acts
- Covered back to that date. The Medicare-only option covers past Medicare sales only. On P&C, a gap of up to 45 days between policies still counts as continuous
- Tail, life and health
- A tail gives you extra time to report claims after you stop buying. It's free for three years once you've been enrolled three years. Otherwise buy one, two or three years at 100%, 160% or 200% of your yearly premium within 30 days, or an unlimited tail at 250%
- Tail, P&C
- One free year, then one or two more years at 100% or 160% of your yearly premium
- Form number
- CNA77697XX (12-2024) for life and health. CNA110002XX (01-25) for P&C
Keep your retroactive date when you switch. Your retroactive date carries over only with no lapse in coverage, so line up the new start date with the day the old policy ends.
Limits, deductibles and defense
The per-claim limit is the most the policy pays on one claim. The yearly aggregate is the most it pays for all claims in a policy year.
| Limit per claim | Aggregate | Deductible |
|---|---|---|
| $1 million | $3 million | $0 on life, health and fixed annuities. $5,000 on variable products and mutual funds |
| $2 million | $2 million | Same as Options A, B and C. Experienced life and health agents only |
| $1 million | $1 million | Medicare only and the P&C options. $5,000 personal lines, $10,000 commercial, $25,000 flood and Level 3 |
| $1 million | $2 million or $3 million | Agency programs, same deductibles by line |
- Defense costs
- Inside the limit. Legal fees come out of the same money that pays a settlement
- Flood, quake and wind
- Capped at $100,000 per claim on P&C
All agents in the program share a total of $50 million a year for life and health and $25 million for P&C, except in New York. A very large loss elsewhere could use some of it up.
Consent to settle and exclusions
- Consent to settle
- No. The insurer can settle a claim as it sees fit. You can't admit fault or agree to a settlement without its approval, which it can't unreasonably refuse
Excluded
- Punitive damages
- Multiple employer welfare arrangements (MEWAs)
- Variable products and mutual funds unless you buy Option C
- Non-Medicare sales on the Medicare-only option
- Long-haul trucking on P&C Levels 2 and 3
- Carrier insolvency. The insurer still defends a covered claim if the carrier was admitted and well rated when you placed it
Who the policy covers
- The agency
- On individual programs, your agency is covered only for claims over your own work. The agency program covers the agency itself
- Employees
- Clerical and support staff while working for you. The P&C agency program covers all employees
- Subproducers
- Not on individual programs. The IMO option covers the IMO's exclusive downline agents
- Independent contractors
- Covered on the P&C agency program while acting for the agency. Nonexclusive downline agents need their own E&O
Included and optional coverage
| Coverage | Included or optional | Limit |
|---|---|---|
| Regulatory defense | Included | $25,000 life and health with no deductible. $20,000 P&C with a $2,500 deductible |
| Privacy claims | Included | $25,000 a claim, $250,000 a year on life and health. P&C has its own endorsement with a $2,500 deductible |
| Social media | Included | Within the policy limit |
| Notary services | Included on life and health | Within the policy limit |
| Military activation | Included on life and health | See the policy |
| Life and health for P&C agents | Optional | Options A, B and C |
How to apply
Pick a program
Choose life and health, P&C or agency, then the option or level that covers everything you sell.
Complete the application
It asks about your licenses, products, revenue, past coverage and claims.
Pick a start date
Coverage starts on the first of a month. Starting this month means confirming you know of no claims.
Bind and pay
Pay in full or make the down payment by card or bank draft.
Get the certificate
Download it from your NAPA account once you're approved.
Sponsored programs can need 30 days or more if you're still getting licensed or appointed with the sponsor.
Claims and risk management
- How to report
- In writing to the insurer at the address on your certificate. NAPA's claims line is 800-593-7657
- When to report
- As soon as you can. On P&C you can report a possible claim before it's made, and you get 30 days after the policy ends to report a claim made while it was active
- Claims handled by
- The CNA insurer on your certificate
NAPA publishes articles on common agent mistakes and how to document client decisions.
Cancellation and renewal
- You cancel
- Through your NAPA account
- The insurer cancels
- Your certificate and state rules control it. Ending the master policy doesn't cut short a certificate you already have
- Refunds
- Yearly payers get back unearned premium, minus a minimum earned amount. Monthly drafts stop. Dues, fees and taxes aren't refunded
- Nonrenewal notice
- Given under the law of the state where your certificate was issued
- Renewal date
- Renews on its own each year unless you cancel the payment authorization in writing
- Payment options
- Pay in full, or monthly by card or bank draft
NAPA E&O alternatives
- EOforLessFrom $374 a year, Medicare only, $1M/$1M, $0 deductibleSame NAPA life and health rates, plus a separate P&C path
- CalSuranceQuote onlyPrograms for NAIFA and NABIP members
- American Agents AllianceQuote only for most agenciesMember program with defense outside the limit
- Travelers through AMBAQuote onlyTravelers policy for life and health agents
- Big I Professional LiabilityQuote onlyDefense outside the limit for independent P&C agencies
See every option in E&O insurance for insurance agents.
Frequently asked questions
How much does NAPA E&O cost?
Option A costs $355 a year for a newly licensed life and health agent and $441 for an experienced one. Solo P&C agents start at $680 and P&C agencies at $980. Each price has its own limit and deductible in the table above, as published in October 2026.
Who issues NAPA's E&O policy?
One or more CNA companies, and your certificate names the exact one. NAPA runs the program and Gallagher Affinity is the licensed broker.
Can a newly licensed agent buy NAPA E&O?
Yes. Within two years of your first life and health license, and with under $100,000 in commissions, you get the lower newly licensed rates.
Are defense costs inside or outside the limit?
Inside. Legal fees reduce what's left to pay the claim.
What happens to prior acts if I switch to NAPA?
They're covered back to the day your continuous E&O began, as long as there's no lapse. Check that date on the new certificate before the old policy ends.
How fast do I get a certificate?
You download it from your NAPA account once you're approved and paid. Coverage starts on the first of the month you pick.
How we researched this review. We based this review on the pricing, terms and product pages published by NAPA E&O, reviewed in October 2026, together with our team's experience working with insurance agents and agency owners since 2008.
Corrections
Vendors change their pricing all the time and they don't email us when they do. So if you see a price on here that's gone up, a plan NAPA E&O quit selling or a contract term that reads different now, let us know and send the link to the page where NAPA E&O has it. Somebody here pulls up that page and checks it before we change anything on ours.