Rockwood Programs review for insurance agents: E&O cost, coverage and policy terms
Agents E&O pays to defend and settle a client's claim that your mistake cost them money. Rockwood Programs is a managing general agency in Delaware that runs a Lloyd's E&O program for retail P&C agents, and it handles underwriting and service for the insurers.
There are three tracks: established agencies, agents licensed three years or less and a surplus lines program for larger agencies and MGAs.
- Best for
- Established retail P&C agencies, plus a separate track for agents licensed three years or less
- Price
- Quote only
- Insurer
- Certain Underwriters at Lloyd's, London
- Lines covered
- Personal and commercial P&C, with some life, accident and health placements
- Policy form
- Claims-made. A claim must be made and reported during the policy period
Our take
Rockwood suits established retail P&C agencies that want a Lloyd's policy whose full form is posted online, so you can read the terms first. Agents licensed three years or less have their own track with $500,000 or $1,000,000 limits.
The tail must be bought within 10 days, and every program is quoted.
Pros
- A separate track for newly licensed P&C agents
- The full policy form is posted online
- Deductible skips defense costs and can vanish after claim-free years
- Employee dishonesty and a free pre-claims hotline included
Cons
- No monthly payment plan
- Only 10 days to buy the tail after the policy ends
- Securities and variable annuity work is excluded
- No current published prices
Who can buy
| Program | Who it fits | Main limits on who can apply |
|---|---|---|
| Established agentsLloyd's program | Retail P&C agencies and agents | Firms doing consulting, claims administration, TPA, wholesale or MGA work, PEOs or crop insurance go to other markets |
| Newly licensed agentsLloyd's program | Agents licensed three years or less | Under $150,000 in yearly commission and no past E&O claims |
| Large agencies and MGAsSurplus lines program | Larger retail agencies, brokers, wholesalers, MGAs and MGUs | Underwritten case by case |
- Newly licensed rules
- Standard lines only, such as personal lines, business owners policies, general liability and workers compensation. No more than 10% of your book with surplus lines insurers, and every insurer you place with must be rated B+ or better by AM Best
- Risk training
- New agents agree to review Rockwood's risk management tools within 90 days of the policy starting
- Prior claims
- The application asks about claims and discipline in the past five years
- Membership required
- No
What it costs
| Program | Limit | Deductible | Price |
|---|---|---|---|
| Newly licensed agents$500,000 limit | $500,000 per claim, $500,000 a year | $5,000 | Quote only |
| Newly licensed agents$1 million limit | $1 million per claim, $1 million a year | $5,000 | Quote only |
| Established agentsLloyd's program | Your choice | $2,500 to $25,000 | Quote only |
| Large agencies and MGAsSurplus lines | Your choice | Set in the quote | Quote only |
Rockwood's newly licensed page, last updated in March 2015, still shows starting premiums of $2,150 and $2,500 a year. Those are 2015 figures, so ask Rockwood for a current quote.
- Renewals
- The newly licensed base premium goes down at each renewal
- Payment options
- No monthly plan. Life and health agents can pay quarterly. Others pay in full or arrange outside premium financing
- How to pay
- Credit card or bank transfer through the online payment portal
- Fees
- Policy fees on the declarations page are fully earned when the policy starts, so they aren't refunded
Compare the programs
| Established agents | Newly licensed | Large agencies and MGAs | |
|---|---|---|---|
| Insurer | Lloyd's | Lloyd's | Not named |
| Limits | Your choice | $500,000 or $1 million | Your choice |
| Deductible | $2,500 to $25,000 | $5,000 | Set in the quote |
| Policy form posted online | |||
| Life and health placements | Incidental | By quote |
The large-agency pages were last updated in March 2021.
Insurer and admitted status
- Issuing insurer
- Certain Underwriters at Lloyd's, London, for the established and newly licensed programs. On the large-agency program, the quote names the insurer
- Several liability
- Each Lloyd's underwriter on the policy pays only its own share of a claim
- Administrator
- Rockwood Programs, a managing general agency in Claymont, Delaware
- States
- Offered nationally. The newly licensed page notes some territory limits
Policy form, prior acts and tail
- Policy form
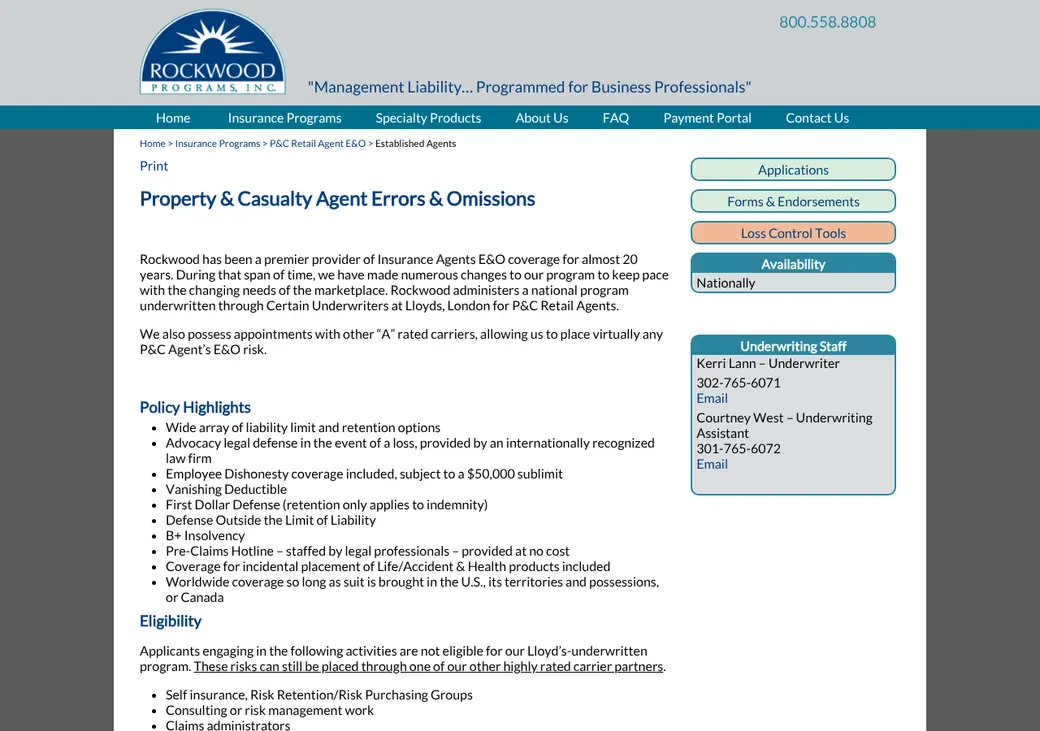
- Claims-made, form LSW224 dated June 2024
- Retroactive date
- The policy covers mistakes made on or after the retroactive date on your schedule, the earliest date of past work it will cover
- Prior acts
- Past mistakes count only if you didn't know about a likely claim when the policy began. A claim another policy already covers stays with that policy
- Tail options
- You can buy 12 extra months to report claims if the insurer cancels or won't renew, you retire, you sell a controlling share or you stop the work. Ask in writing within 10 days of the end date. The cost is up to 150% of your last full premium
- Notice of circumstances
- If you report facts that could lead to a claim during the policy, a later claim from those facts counts as made during the policy
Claims-made means the policy in force when the claim is made pays it. Keep your file notes. The policy makes records of the work behind a claim a condition of coverage.
Limits, deductibles and defense
The per-claim limit is the most the policy pays on one claim. The aggregate is the most it pays in a policy year. The deductible is your share of each claim.
The price table above lists each program's limits and deductibles.
- Defense costs
- On the established form, defense costs sit outside the per-claim limit until $1 million of defense has been spent across all claims. After that, defense uses up the limit. The aggregate counts both damages and defense
- Extra defense limit
- Endorsement LSW526 adds $250,000 for defense that doesn't reduce your limits
- Deductible
- Applies to damages only, not to defense costs
- Claim-free credit
- After three claim-free years with these underwriters, the deductible is waived on the next claim that pays damages
Consent to settle and exclusions
- Consent to settle
- The insurer can't settle without your consent. If you refuse a settlement it recommends, it pays no more than that settlement amount plus defense costs to that date
Excluded
- Insurer insolvency, unless the insurer was rated B+ or better by AM Best, or similar, when you placed or renewed the policy
- Work as an adjuster, reinsurance underwriter, MGU or MGA
- Variable annuities, mutual funds, stocks, bonds and securities law claims
- Work as a lawyer, accountant, notary, investment adviser, tax adviser or real estate agent
- Work done without a current license
- Mixing client money with your own, or losing client funds
- MEWAs, captives, risk retention groups and other self-funded plans
- Punitive damages, fines and penalties
- Bodily injury, property damage, libel, privacy and discrimination claims
- Performance bonds
Who the policy covers
- The agency
- The person or firm named on the schedule
- Employees
- Partners, officers, directors and employees, plus former ones for past work
- Independent contractors
- Covered for work done for you under a written contract. The application asks whether to add 1099 contractors
Included and optional coverage
| Coverage | Included or optional | Limit |
|---|---|---|
| Employee dishonesty | Included | $50,000 aggregate |
| Cyber liability | Optional endorsement | $100,000 |
| License and disciplinary defense | Included, no deductible | Set on the schedule |
| Lost earnings for court days | Included, no deductible | Set on the schedule |
| Worldwide coverage | Included when suit is filed in the US or Canada | Within the policy limit |
| Pre-claims hotline | Included, no charge | Staffed by legal professionals |
Stand-alone cyber is available from other markets. The large-agency program lists defense outside the limit, first-dollar defense, cyber and employment practices as options.
How to apply
Pick the program
Established agents, newly licensed agents or the large-agency program.
Complete the application
Use the online application, or send it by email, fax or mail.
Gather your numbers
License dates, staff, ownership, premium and commission by line, and your current E&O insurer and retroactive date.
Answer claim questions
Five years of claims and discipline, plus cyber security questions.
Review the quote and bind
Completing the application doesn't bind you or the insurer.
Claims and risk management
- How to report
- Send written notice to the underwriters right away, and ask Rockwood for the address
- When to report
- Immediately, during the policy period. Report circumstances that could become claims too
- Claims help
- A free pre-claims hotline staffed by legal professionals
Policyholders also get loss control tools behind a login.
Cancellation and renewal
- If you cancel
- You get back less than the unused share of the premium, because the policy uses a short-rate refund
- If the insurer cancels
- At least 30 days' notice, or 10 days for nonpayment. You get back the unused premium day for day
- Renewal
- A higher renewal price or new terms doesn't count as a nonrenewal for the tail option
Rockwood Programs alternatives
- Big I Professional LiabilityQuote onlySwiss Re program with defense outside the limit
- Utica NationalQuote onlyDirect insurer for P&C agencies, rated A (Excellent)
- NAPA E&OFrom $680 a year, solo P&C, $1M/$1M, $5,000 deductiblePublished P&C prices and online sign-up
- MarkelQuote onlySpecialty insurer covering MGAs and wholesalers
- Axis Insurance ServicesQuote onlyBroker placing E&O for larger agencies and MGAs
See every option in E&O insurance for insurance agents.
Frequently asked questions
How much does Rockwood E&O cost?
Every program is quoted. A Rockwood page last updated in March 2015 still lists newly licensed starting premiums, so ask Rockwood for today's rate.
Are defense costs outside the limit?
Partly. They sit outside the per-claim limit until the first $1,000,000 of defense has been spent. After that, defense reduces it.
Can I pay monthly?
No. Life and health agents can pay quarterly, and everyone else pays in full or uses outside premium financing.
Who counts as newly licensed?
An agent licensed three years or less with under $150,000 in yearly commission and no past E&O claims. After three years you move to the standard program.
How we researched this review. We based this review on the terms and product pages published by Rockwood Programs, reviewed in October 2026, together with our team's experience working with insurance agents and agency owners since 2008.
Corrections
Vendors change their pricing all the time and they don't email us when they do. So if you see a price on here that's gone up, a plan Rockwood Programs quit selling or a contract term that reads different now, let us know and send the link to the page where Rockwood Programs has it. Somebody here pulls up that page and checks it before we change anything on ours.