SIMG review for insurance agencies: fees, carrier access and book ownership
SIMG is a Minnesota network that gives small agencies subcodes under its master codes with carriers such as Travelers and The Hartford. It works in 11 states.
Full access costs $300 a year or $600 for life. You keep 70% to 95% of each commission, and SIMG pays you monthly.
A carrier appointment is the contract that lets you sell a carrier's policies. When the network holds it, that contract is its master code, and you work under it on a subcode, a code issued in your name beneath the network's.
The commission split is the part of each commission the network holds back. Profit sharing is the bonus carriers pay once a year for low claims and growth. Your book is your clients plus their expirations, meaning the renewal records you need to keep or sell the business.
- Best for
- Small and startup agencies in 11 states that want low fixed costs and subcodes with major carriers
- Entry fee
- $0
- Yearly fee
- $300, or $600 once for life
- Commission share
- SIMG keeps 5% to 30%
- Carrier access
- A subcode under SIMG's master codes
- Startups
- Yes
Our take
SIMG suits a startup or small agency that wants the lowest fixed cost in this group. It says you own your clients and keep renewals even after you leave.
SIMG doesn't place or service business for you, and its split can be as low as 70% to you. Carriers can also drop you for low activity.
Pros
- Very low yearly or lifetime fee
- Says you keep renewals after you leave
- Takes startups
- Free to use outside carriers
- Monthly direct deposit with statements
Cons
- Keeps up to 30% of commission
- No placement or service desk
- No path to your own codes
- Producer Agreement is not public
Who they take
- Startups
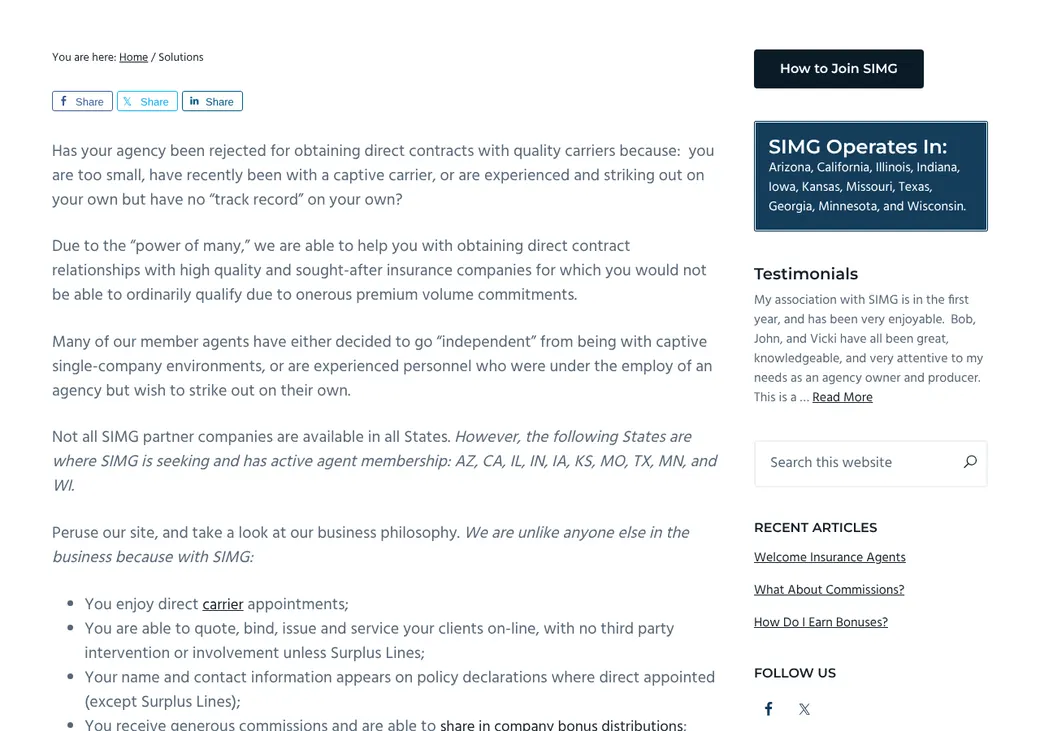
- Yes. You send five sample home and five sample auto declarations pages so SIMG can match carriers
- Captive agents
- Yes, though carriers usually won't contract with you until your captive contract has ended
- Requirements
- A questionnaire, the access fee, active licenses and current E&O on file
- Production minimums
- None for SIMG. Carriers set their own, from about $15,000 a year in personal lines
- States
- Arizona, California, Georgia, Illinois, Indiana, Iowa, Kansas, Minnesota, Missouri, Texas and Wisconsin
- Lines
- Personal and commercial P&C, excess and surplus lines through partners, plus life, health and annuities
What it costs
SIMG charges a small access fee, either every year or once for life. On top of that it keeps part of each commission, from 5% to 30% depending on your Producer Agreement.
| Fee | Amount | How often |
|---|---|---|
| Full access | $300 | Yearly |
| Full access, lifetime | $600 | Once, in place of the yearly fee |
| Limited access | $150 | Yearly |
| Limited access, lifetime | $300 | Once, in place of the yearly fee |
| Commission kept | 5% to 30% | Every commission payment |
Fees as of October 2026, from simginsurance.com. Limited access covers only life, health, extended care and forced-order bank products, which banks require when a homeowner's coverage lapses.
How you get carrier access
Your own appointments
SIMG does not describe a path to your own codes. You may use outside carriers alongside it.
The network's code
Members get subcodes under SIMG's master codes, with their own carrier logins. A few carriers start you as a house producer, writing under SIMG's own code, until you build a book.
- Who holds the appointment
- SIMG holds the master codes
- Carriers
- Travelers, The Hartford, Guard, Foremost, Bristol West, Kemper and others. Mercury is offered in Illinois and AAA in parts of Illinois and Indiana
How you get paid
- Who the carrier pays
- SIMG, which pays you by direct deposit once a month, by the third Wednesday
- Commission schedule
- 70% to 95% to you, set in your Producer Agreement
- Profit sharing
- After $30,000 a year with a carrier, members over that level share half of any SIMG bonus from it
Your book and leaving
SIMG says you own your business at all times, and you keep renewals and the right to contact your clients during membership and after. That holds unless you abandon the book or commit regulatory misconduct.
- Who owns the expirations
- You, according to SIMG
- Your clients after you leave
- You keep renewals and can keep soliciting them
- Restrictions
- You are not limited to SIMG carriers
Term and exit
- Agreement term
- Yearly, or a lifetime option
- Ending it
- SIMG or a carrier can end it, including for lack of activity
Technology, E&O and support
Technology
- No required agency management system
- Most carriers work with the comparative rater you already use
E&O
You must keep current E&O on file to join and to be paid.
Help you get
- Excess and surplus lines through partner wholesalers
- Carrier training, webinars and visits
- Brochure and press release templates
- Monthly commission statements
Who owns the network
- Buys member agencies
- No
SIMG alternatives
- Greater Midstates Insurance AgencyNo monthly duesOne-time fee, no dues, six central states
- FireflyNo monthly duesWrites on Firefly's code and keeps 10%. Moving its carrier business costs 30% of a year's commission
- Smart ChoiceNo monthly feeNo entry or monthly fee, keeps 30% until a set commission level, then nothing
- Combined Agents of AmericaMember-owned, for established agencies in the central states
- Insurance Pro Agencies20% splitKeeps 20%, at least $495 a month, and publishes its full agreement
See every option in insurance agency clusters and networks.
Frequently asked questions
How much does SIMG cost?
Full access is $300 a year or $600 for life. SIMG also keeps 5% to 30% of each commission.
Do I own my book with SIMG?
SIMG says yes, and that you keep renewals and solicitation rights after you leave.
Does SIMG take startup agencies?
Yes. You send sample declarations pages so it can match you with carriers.
When does SIMG pay commissions?
Once a month by direct deposit, by the third Wednesday.
How we researched this review. We based this review on the pricing, terms and product pages published by SIMG, reviewed in October 2026, together with our team's experience working with insurance agents and agency owners since 2008.
Corrections
Vendors change their pricing all the time and they don't email us when they do. So if you see a price on here that's gone up, a plan SIMG quit selling or a contract term that reads different now, let us know and send the link to the page where SIMG has it. Somebody here pulls up that page and checks it before we change anything on ours.